The Hidden Medicare Cost That Could Add Thousands to Your Retirement
Expenses
Medicare Part B May Rise to $209.50. That’s Not the Number Affluent Retirees Should Be Watching.
The projected 2027 Medicare premium increase looks modest. But for higher-income retirees, an overlooked Medicare rule could add thousands of dollars to annual healthcare costs—and decisions made before year-end may determine what happens next.
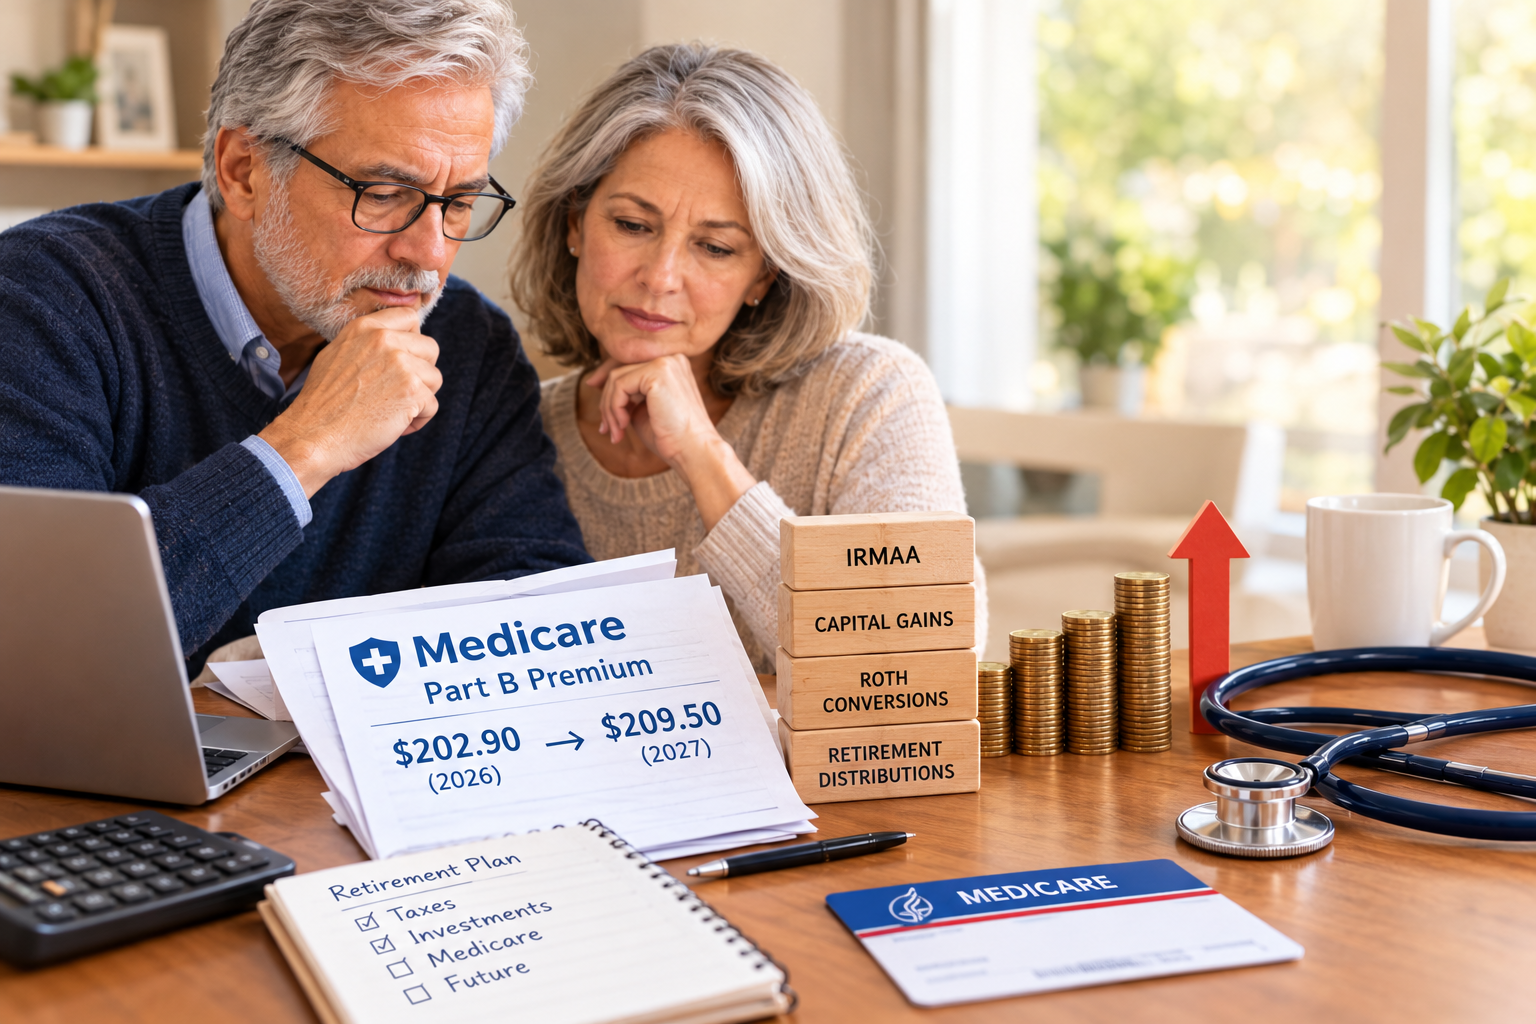
Social Security recipients received encouraging news this month with the announcement of a 3.6% cost-of-living adjustment (COLA) for 2027, translating to approximately $75 more per month for the average retired worker. Meanwhile, the standard Medicare Part B premium is projected to increase from $202.90 in 2026 to $209.50 in 2027, according to the Medicare Trustees Report.
If that projection holds, the $6.60 monthly Medicare increase would consume a relatively small portion of the average Social Security adjustment, leaving approximately $68 in additional monthly income before taxes and other deductions. While the final Medicare premium has not yet been announced, the preliminary outlook is encouraging for retirees paying the standard premium.
For affluent retirees, however, the more significant financial concern isn’t necessarily the standard premium increase. It’s an often-overlooked provision known as the Income-Related Monthly Adjustment Amount (IRMAA), which can substantially increase Medicare costs when income exceeds certain thresholds.
Financial decisions involving Roth conversions, capital gains, and retirement distributions can trigger these higher premiums two years later. With year-end approaching, understanding that relationship could make a meaningful difference in retirement planning.
The Hidden Medicare Cost That Can Turn One Dollar Into Thousands
Most retirees understand that higher income generally leads to higher taxes. What many don’t realize is that Medicare operates under different rules, where crossing an income threshold by even one dollar can trigger an entirely higher level of monthly premiums.
For 2026, the first IRMAA threshold begins when modified adjusted gross income (MAGI) exceeds $109,000 for single filers or $218,000 for married couples filing jointly. Beneficiaries above these thresholds pay additional premiums for Medicare Part B and, if enrolled in prescription drug coverage, Part D.
Consider a married couple who are both enrolled in Medicare. If their MAGI exceeds the applicable 2026 threshold by even one dollar, their combined additional Medicare costs could reach approximately $2,297 annually, including both Part B and Part D surcharges.
For households with substantial retirement accounts, taxable investments, or multiple income sources, a required minimum distribution, realized capital gain, or Roth conversion could be enough to cross an IRMAA threshold. The financial impact becomes even more important when considering how Medicare determines which year’s income to use.
Why Your 2027 Medicare Premium May Have Been Decided in 2025
One of the most frequently overlooked aspects of IRMAA is Medicare’s two-year income lookback. Social Security generally determines income-related Medicare premiums using modified adjusted gross income reported on a tax return from two years earlier.
For 2027, that generally means reviewing income from 2025. Likewise, financial decisions made during 2026 will generally influence Medicare premiums in 2028.
Someone who completed a substantial Roth conversion or realized significant investment gains in 2025 may face higher Medicare premiums in 2027, even if their current income is considerably lower.
Certain qualifying life-changing events, including retirement, reduced work hours, divorce, or the death of a spouse, may allow beneficiaries to request a new income-related premium determination from Social Security. However, not every decline in income qualifies.
A strategy that appears attractive from an immediate tax perspective may create additional Medicare expenses two years later. That doesn’t necessarily make the decision wrong, but it reinforces why retirement tax planning should extend beyond a single calendar year.
When Paying More for Medicare Might Actually Make Financial Sense
As year-end approaches, many affluent retirees evaluate whether to complete additional Roth conversions, recognize investment gains, or adjust retirement distributions. These decisions are often made to manage tax brackets and improve long-term tax efficiency, but Medicare costs deserve a place in that analysis.
Consider a married couple evaluating whether to convert an additional $25,000 from a traditional IRA to a Roth IRA before December 31. Depending on their other income, the conversion could push them into a higher IRMAA tier in 2028. Avoiding the conversion might prevent that additional Medicare expense, but it could also leave more money in tax-deferred accounts, potentially increasing future required minimum distributions and taxes.
The analysis becomes more complex when considering a surviving spouse, who may eventually face higher individual tax rates and lower Medicare income thresholds after transitioning from married filing jointly to single filing status.
In some circumstances, accepting an IRMAA surcharge may still produce a better long-term financial outcome. The objective shouldn’t necessarily be to eliminate every Medicare surcharge, but to evaluate whether the benefits of a particular strategy outweigh its combined tax and healthcare costs.
The Boutique Family Office™ Perspective: Look Beyond the Medicare Premium
Traditional retirement planning often addresses Social Security, Medicare, taxes, and investments as separate decisions. Yet for affluent families, these areas are closely connected, and focusing on one expense in isolation can create unintended consequences elsewhere.
A Roth conversion may increase Medicare premiums while reducing future required minimum distributions. Capital gains may create additional taxable income but support an appropriate portfolio reallocation. Taking distributions earlier in retirement might increase near-term taxes while improving flexibility later.
At Advanced Wealth Management, our Boutique Family Office™ approach incorporates these relationships into our Strategic Wealth Alpha GPS™ Retirement Roadmap, evaluating retirement income, taxes, investments, healthcare costs, and long-term wealth preservation together.
Rather than asking only whether a strategy will increase Medicare premiums, the more useful question is whether it improves the household’s overall financial position throughout retirement.
What Affluent Retirees Should Consider Before December 31
Although the income used to determine most 2027 Medicare surcharges has already been reported, decisions made before the end of 2026 may still influence Medicare costs in 2028.
Retirees considering additional Roth conversions, capital gains, or retirement distributions should evaluate their projected year-end MAGI and proximity to an IRMAA threshold alongside their broader tax and retirement income strategy. Those who have experienced qualifying life-changing events may also want to review whether an existing surcharge is eligible for reconsideration.
For households with substantial tax-deferred assets, thoughtful coordination of these decisions can help reduce unexpected expenses while preserving long-term financial flexibility.
The Bottom Line
The projected 2027 Medicare Part B premium increase may offer welcome relief, but for affluent retirees, the larger Medicare expense often isn’t the standard annual increase. It’s the potential surcharge created by income decisions made years earlier.
Understanding how Medicare, taxes, and retirement distributions interact can help families make better-informed decisions. Sometimes that means avoiding an unnecessary surcharge. In other circumstances, accepting higher Medicare premiums may support a more favorable long-term outcome.
The goal isn’t simply to minimize Medicare premiums or this year’s taxes. It’s to preserve more of your wealth by understanding how today’s financial decisions affect tomorrow’s expenses.
Discover the Hidden Tax Secrets That Could Be Eroding Your Retirement Wealth
Medicare IRMAA surcharges are just one example of how routine financial decisions can create unexpected retirement expenses. From required minimum distributions and Roth conversions to the taxation of Social Security benefits, the interaction between retirement income sources can meaningfully affect how much wealth you keep.
Our complimentary Hidden Tax Secrets Guide explores often-overlooked tax considerations and strategies that may help improve tax efficiency and preserve more of your retirement wealth.
Your GPS to Holistic Retirement Planning
Today’s markets create an unusual opportunity: stocks are near record highs while high-quality bonds are offering meaningful income again. But deciding between stocks, bonds, and cash is only one part of building a retirement plan.
The bigger question is: Is your wealth organized around what you need it to accomplish—and when you’ll need it?
That is why I created Your GPS to Holistic Retirement Planning.
In this complimentary course, I walk you through how to think beyond a single investment portfolio and build a more coordinated retirement strategy, including:
- How to turn your savings into reliable retirement income
- How to position money for Income Now, Income Later, Growth, and Legacy
- How to coordinate investments and withdrawals with your tax strategy
- How to prepare for inflation, healthcare costs, market volatility, and longevity
- How to incorporate estate and legacy goals into your broader retirement plan
Markets will change. Your retirement goals shouldn’t depend on predicting what happens next.
Start Your Free Retirement Planning Course →
Retire once. Stay retired.
Complimentary retirement course + workbook
Let’s build a stronger, smarter plan together.
Schedule Your Retirement Strategy Review
Could your retirement income or tax decisions be creating Medicare expenses you haven’t anticipated?
At Advanced Wealth Management, our Boutique Family Office™ approach integrates proactive tax management, Medicare and Social Security planning, retirement income strategies, and long-term wealth preservation through our Strategic Wealth Alpha GPS™ Retirement Roadmap.
Schedule your free consultation today.
Important Disclosure: This article is for educational and informational purposes only and does not constitute personalized investment, tax, legal, accounting, insurance, or medical advice. The $209.50 Medicare premium is a projection, and the IRMAA example uses confirmed 2026 thresholds and surcharges rather than finalized 2027 figures. Actual costs depend on individual circumstances. Consult qualified professionals before making financial decisions. Advisory services are offered through Advanced Wealth Management, LLC, a Florida-registered investment adviser doing business as Boutique Family Office™.