Clearing Zombie Cells: The New Science of Staying Independent Longer
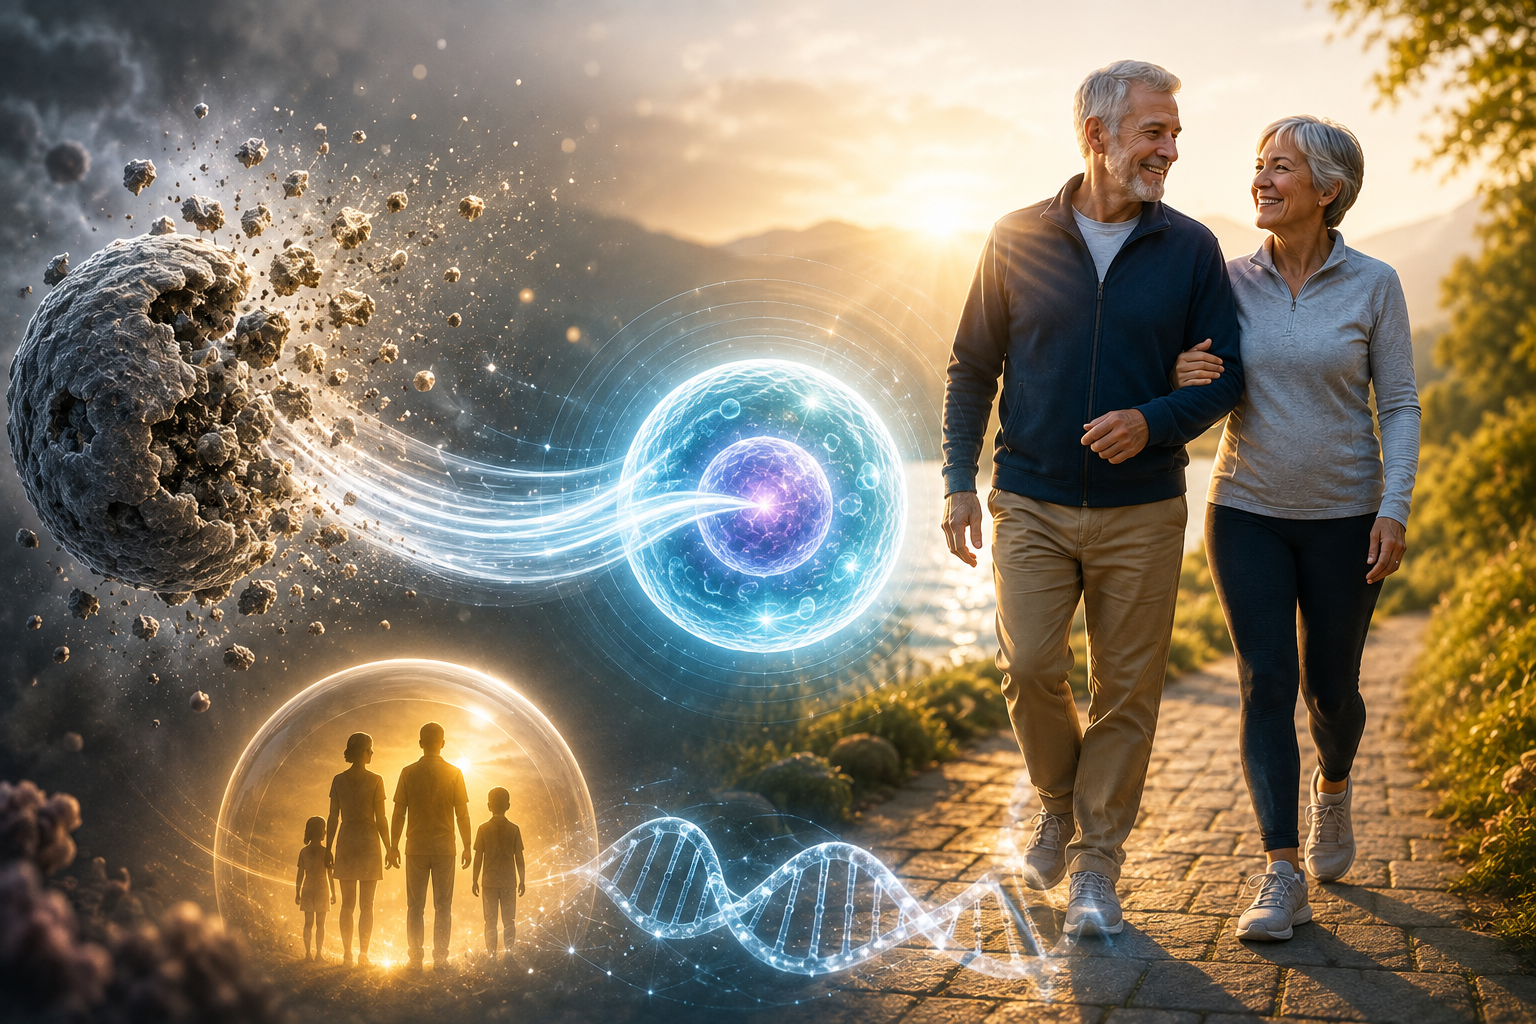
Now that America has just celebrated its 250th birthday in 2026, this week’s longevity blog looks at one of the strangest and most promising frontiers in modern healthspan science: senolytics, therapies being studied for their ability to help the body clear out “zombie cells.”
Put simply, the future of retirement planning may depend on an unexpected biological question: What if your cells could take out the trash better?
Clearing Biological Clutter: The Promise of Senolytics
To understand why active retirement timelines are expanding far beyond conventional assumptions, we need to examine a major breakthrough in geroscience: senolytics.
As our bodies move through decades of active use, some cells accumulate environmental stress and damage. Instead of clearing away through the body’s normal self-cleaning processes, these cells enter a state of permanent arrest. In longevity science, they are technically known as senescent cells, but they are often called “zombie cells.”
A zombie cell is not dead, but it is no longer functioning normally. It is a little like an employee who stopped doing productive work but still shows up to the office every morning, occupying a desk and spending the day sending disruptive emails to the rest of the team.
Those “disruptive emails” are part of what researchers call the senescence-associated secretory phenotype, or SASP. The practical point is that senescent cells can release inflammatory signals that affect surrounding tissues, interfere with repair, and contribute to the low-grade inflammation often associated with aging. Senolytics Review PDF
This is where senolytics become so interesting. Senolytic agents are being studied for their ability to selectively help the body remove senescent cells by targeting the survival pathways those cells use to linger. Journal of Internal Medicine (Note: For deep research into these pathways, see the file titled Journal of Internal Medicine – 2020 – Kirkland – Senolytic drugs from discovery to translation.pdf).
One of the most heavily evaluated combinations is Dasatinib and Quercetin, often shortened to D+Q. Dasatinib is a prescription medication used in oncology. Quercetin is a plant-based flavonoid found in foods such as apples, onions, and berries, and is also available as a supplement.
Early human research has shown encouraging signals, including potential reductions in senescent-cell burden and improvements in physical function in certain study populations. D+Q Pilot Study PDF
The Fiduciary Caution Flag
This is an advanced, developing medical field, not a casual wellness trend. Dasatinib is a serious prescription drug, and even natural compounds can interact with medications or create unexpected risks in the wrong individual. Senolytics belong strictly in the category of physician-guided medical research and care, not self-experimentation based on a headline, podcast clip, or supplement ad. The promise is real, but medical supervision is mandatory.
Why Independence Is the Real Prize
The ultimate goal of senolytics is not cosmetic aging. The deeper prize is function.
Can you keep walking comfortably, traveling confidently, recovering quickly from injury, living independently at home, and remaining actively involved with the people and activities that give life meaning? That is healthspan.
Frailty is one of the biggest unmanaged threats to a modern retirement because it completely alters the family picture. It shifts housing choices, changes lifestyle demands, alters monthly cash flow, and creates heavy emotional and caregiving stress for your spouse or adult children.
If senolytics and precision medicine help preserve physical and cognitive function longer, they support what researchers call compressed morbidity: shortening the period of serious illness, disability, or dependency near the end of life. This represents a monumental paradigm shift—not because it eliminates long-term care risk entirely, but because it radically changes how families must prepare for it.
A New Long-Term Care Conversation
If health technology helps people stay active and autonomous longer, long-term care planning does not disappear. It changes.
The traditional conversation often assumes a long, slow, gradual physical decline. But a healthier aging curve means care may be needed much later in life, for a shorter duration, or in a more concentrated way. This shifts the planning question from a passive, “How do we pay for care?” to a proactive, “How do we preserve choice, liquidity, and family confidence if care is needed?”
At Boutique Family Office™, we exit the product-first mentality and help high-net-worth families evaluate three broad paths to navigate this modern reality:
Review Existing LTC Coverage: Older long-term care policies may still provide meaningful protection, but they must be reviewed against today’s true care costs, premium histories, lifestyle preferences, and your overall retirement asset location. A policy bought 15 years ago may no longer align with today’s landscape.
Consider Hybrid LTC Solutions: Hybrid policies combine standard long-term care benefits with life insurance or annuity assets. They often appeal to families who want robust care protection while preserving the underlying capital value for their heirs if care is never needed. These strategies require careful analysis regarding liquidity, guarantees, and tax treatment.
Build an Intentional Self-Funded Care Reserve: For higher-net-worth families, self-funding is highly realistic, but it should be structured purposefully. The critical question is determining which assets will be liquidated, in what specific sequence, with what tax impact (bracket management), and how the surviving spouse remains fully insulated from market drawdowns and sudden tax spikes.
The right answer is rarely a single product; it is a coordinated framework established long before a stressful medical moment arrives.
Planning for Longer Independence
Senolytics may become one of the important longevity tools of the coming decades, or they may become one useful piece of a much larger health abundance puzzle. Either way, the direction of travel is clear: aging is being studied more seriously, measured more precisely, and targeted more directly than ever before.
Your retirement roadmap must evolve alongside these developments.
At Boutique Family Office™, we believe a modern retirement strategy must simultaneously account for both wealthspan and healthspan. True financial security requires your income, tax planning, globally diversified portfolios, healthcare reserves, estate documents, and family communication structures to work together on a single dashboard.
The goal is not just to live longer. The goal is to preserve your independence, protect your spouse, eliminate family confusion, and maintain your freedom of choice when it matters most.
Your Next Step
If this longevity briefing has made you rethink the connection between advanced health science and your financial future, we invite you to take the next step.
Start with our free course, Your GPS to Holistic Retirement Planning, designed to help you understand how income, proactive tax planning, investments, healthcare coverage, and legacy optimization fit together into a single, synchronized strategy.
You can also schedule a confidential meeting with Advanced Wealth Management / Boutique Family Office™ to discuss how your financial plan can be engineered to support the extended, active life you want to live.
Retire once. Stay retired.
Complimentary retirement course + workbook
Let’s build a stronger, smarter plan together.
Schedule your free consultation today.
Important Disclosure: This content is for informational and educational purposes only and should not be considered personalized investment, tax, legal, accounting, insurance, or medical advice[cite: 12, 13]. The health-related information is educational and should not be treated as a medical diagnosis or prescription[cite: 12]. Always consult your physician or a qualified healthcare provider before making changes to your medications, supplements, testing, or health routine[cite: 12]. Do not use prescription medications or senolytic protocols except under the direct supervision of a qualified medical professional[cite: 12]. Investing involves risk, including the possible loss of principal[cite: 12, 13]. Insurance and long-term care strategies should be reviewed with qualified professionals based on your personal situation. Advisory services are offered through Advanced Wealth Management, LLC, a registered investment adviser in Florida doing business as Boutique Family Office™.
At AWM, Our Fiduciary Duty Principles™ Define Our Commitment
This commentary is for informational and educational purposes only and is not investment, tax, legal, or accounting advice. Any investment involves risk, including the possible loss of principal. Private and alternative investments may be illiquid, may involve higher fees, may use leverage, may have limited transparency, and may not be suitable for all investors. Liquidity features (including redemption/repurchase programs) are not guaranteed and may be limited, suspended, or modified. Distributions are not guaranteed and may be sourced from factors other than operating cash flow. Tax treatment is complex and investor-specific; consult your tax advisor. Any offering is made only through applicable offering documents and only to eligible investors where lawful.
How We Can Help You
At AWM, we provide personalized, comprehensive guidance for individuals and families. Our services offer peace of mind and confidence through every stage of your financial journey:
- Investment Management: Our globally diversified, tax-efficient portfolios are designed for resilience across market conditions.
- Proactive Tax Planning: We focus on tax-efficient strategies for both accumulation and distribution phases, helping you manage liabilities.
- Integrated Goals-Based Planning: Align all life goals into a unified financial plan to navigate transitions strategically.
Contact AWM today to schedule a confidential consultation and connect with an advisor who can help you achieve your financial goals. For assistance, reach out to us at Service@awmfl.com.
Thank you for your continued trust and engagement.
Tony Gomes, Author, MBA
CEO and Founder
Advanced Wealth Management