2027 Social Security COLA: What You’ll Actually Keep
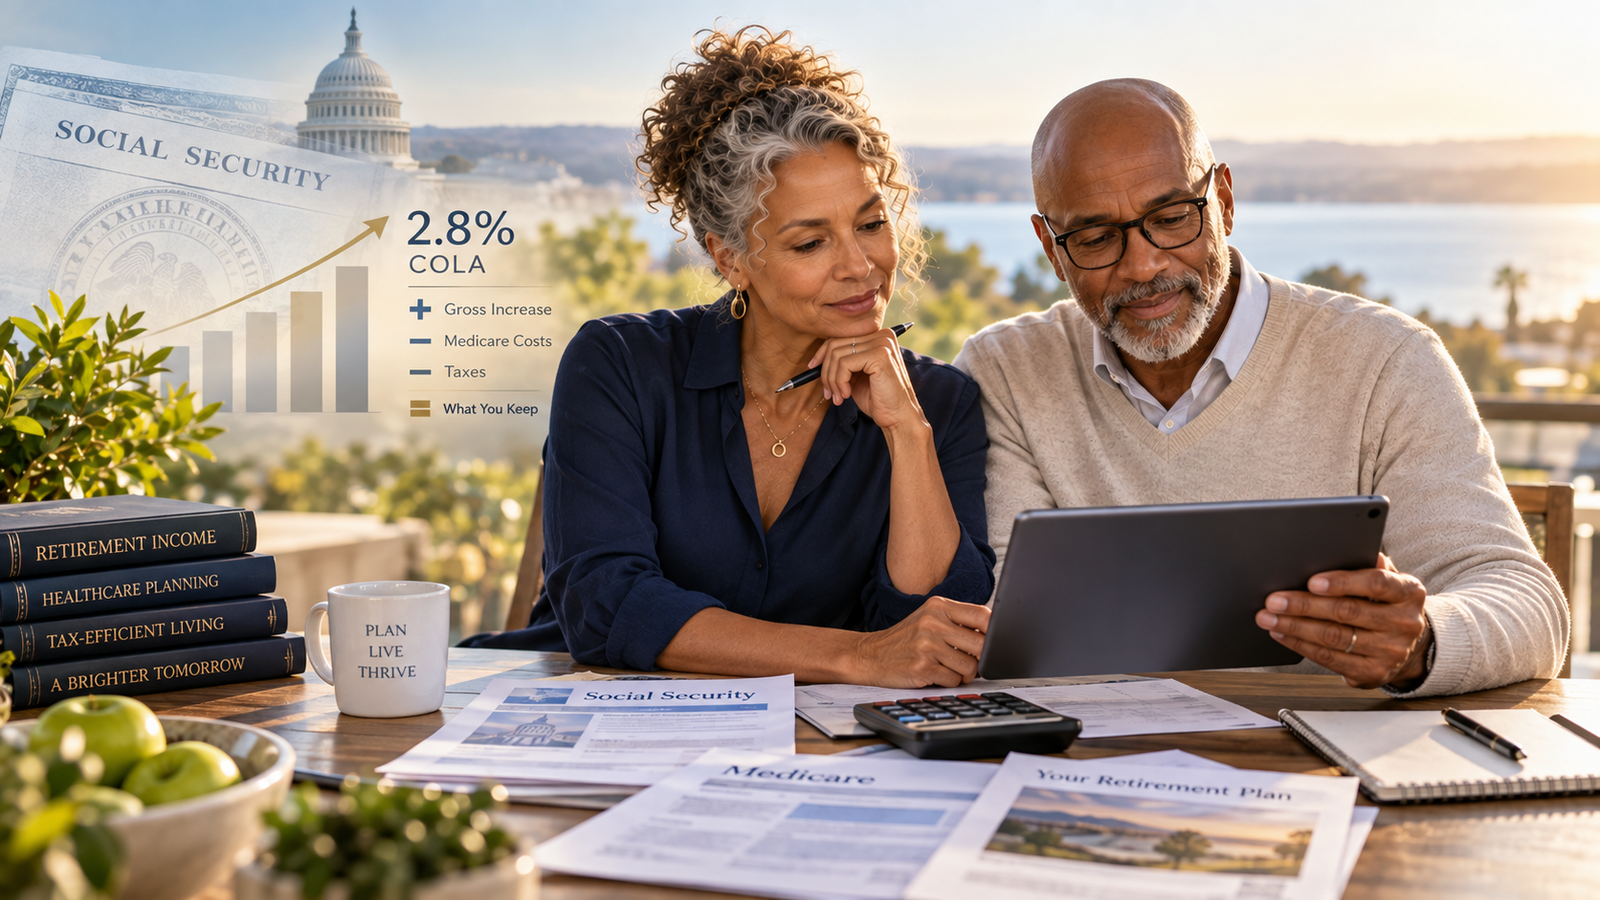
The 2027 Social Security cost-of-living adjustment is 2.8%. But Medicare premiums, taxes, and your actual household expenses will determine how much additional spending power you really gain.
The 2027 Social Security COLA is now official. The increase is 2.8%, matching the COLA beneficiaries received in 2026. That means Social Security benefits will receive another adjustment designed to help keep pace with inflation. But the percentage that makes the headline is not necessarily the number that determines how much better off you feel next year. The more important question is:
How much additional purchasing power will actually remain after Medicare premiums, taxes, and the expenses that matter most to your household?
What the 2.8% COLA Actually Means
Social Security’s COLA is determined by a formula based on the Consumer Price Index for Urban Wage Earners and Clerical Workers, known as CPI-W. The calculation compares the average CPI-W for July, August, and September with the corresponding third-quarter average from the prior year.
The resulting percentage becomes the annual COLA.For 2027, that calculation produced a 2.8% COLA. That is the same percentage beneficiaries received in 2026. Consider a retiree receiving $2,000 per month in Social Security benefits.
- A 2.8% COLA would increase the gross benefit by approximately :$56 per month
- That would bring the monthly benefit to roughly: $2,056 per month
- Over a full year, that represents approximately: $672 in additional gross Social Security income
That increase is helpful. But for most retirees, the bigger question is not the gross increase. It is how much additional income remains after the other pieces of retirement planning are considered.
Your Net Raise Matters More Than the Headline
For many retirees, Medicare Part B premiums are deducted directly from Social Security benefits. That means the increase shown in your Social Security benefit may not equal the increase that ultimately reaches your bank account.The 2026 standard Medicare Part B premium is $202.90 per month. The 2026 Medicare Trustees Report estimated the standard 2027 premium at $209.50 per month, although that figure should not be treated as final until Medicare officially establishes the 2027 premium. Using the $2,000 Social Security example:
- A 2.8% COLA adds approximately:$56 per month
- If the currently estimated $209.50 Medicare Part B premium becomes the final 2027 amount, the increase from the 2026 premium would be approximately: $6.60 per month
- That would leave approximately:$49.40 of additional monthly income before considering taxes or other deductions
Medicare would not consume most of the COLA. But it illustrates an important retirement planning lesson:
The headline increase is only one piece of your actual retirement income picture.
Taxes Can Change the Real Impact of a COLA
A higher Social Security benefit can also affect your tax situation. Depending on your income, up to 85% of your Social Security benefits may be taxable. That matters because many retirees receive income from several sources, including IRA withdrawals, pensions and investment accounts. Even a modest increase in Social Security can interact with that income and affect the household’s overall tax picture.
Medicare planning adds another layer. Income-related Medicare adjustments, commonly known as IRMAA surcharges, generally use income from two years earlier. As a result, retirement income decisions made today can influence future Medicare costs. This is why retirement tax planning should look beyond a single calendar year. The goal is not simply to reduce this year’s taxes. It is to coordinate income and tax decisions throughout retirement.
Inflation Is Personal
There is another issue with COLA that often gets overlooked. The Social Security adjustment is based on a broad national measure of inflation. Your personal inflation rate may look very different.
One retiree may spend more on travel and entertainment. Another household may feel greater pressure from healthcare, housing, insurance and everyday living expenses. A national inflation number cannot fully capture your personal retirement experience. This helps explain why retirees may receive a COLA increase yet still feel their purchasing power declining. Your retirement plan should reflect your actual expenses and income sources. It should also account for your priorities and long-term goals—not just a national average.
Social Security Is One Piece of the Retirement Puzzle
For many retirees, Social Security is an important source of income. However, a successful retirement strategy requires coordinating much more than one benefit payment. Your retirement income plan may include Social Security, portfolio withdrawals, pensions and other tax-efficient income sources. The question is not simply:
“How much Social Security will I receive?”
The better question is:
“How does Social Security work with everything else in my retirement plan?”
This is the foundation behind a holistic retirement approach. A comprehensive retirement strategy connects income planning, investment decisions, taxes, healthcare, and legacy goals into one coordinated plan.
A Boutique Family Office™ Lens: Why COLA Decisions Require a Bigger Picture
A Social Security adjustment may arrive as one number, but retirement decisions rarely happen one at a time. A change in Social Security income can influence other areas of your financial life, including how much you withdraw from your portfolio, whether you remain within a preferred tax bracket, whether Roth conversion opportunities still make sense, how Medicare premiums may change in future years, and how much income remains available for lifestyle spending and legacy goals.
This is where a Boutique Family Office™ approach is different from traditional retirement planning. Instead of looking at Social Security, investments, taxes, healthcare, and estate planning as separate conversations, a comprehensive wealth strategy connects these decisions together.
For example:
- A retiree receiving a higher Social Security benefit may not need to increase portfolio withdrawals as much.
- A retiree with significant IRA assets may need to consider how future required minimum distributions affect taxes and Medicare costs.
- A family focused on wealth transfer may want to coordinate current income decisions with future estate planning opportunities.
- The goal is not simply to maximize one retirement benefit.
- The goal is to maximize the efficiency of your entire financial system.
- That is the foundation of a true retirement strategy.
Five Retirement Planning Moves for 2027
The COLA has now been announced. The focus should shift from prediction to planning.
1. Put Your Actual Increase Into Your Income Plan
Update your retirement income projection using your new Social Security benefit rather than relying on a general percentage.
2. Review Your Medicare Costs
Your actual increase in spendable income depends partly on Medicare premiums and other healthcare expenses.
3. Compare Inflation to Your Household Budget
Your personal expenses matter more than a national inflation average. Review the categories that have the greatest impact on your lifestyle.
4. Review Your Retirement Income Strategy
Make sure Social Security, investment withdrawals, pensions, and cash reserves are working together.
5. Consider the Tax Impact
Review how the additional income affects Social Security taxation, Roth conversion opportunities, required distributions, and future Medicare premiums.
Go Deeper: Your Social Security Optimization Guide
The 2027 COLA is only one part of the Social Security equation. The bigger decisions involve when to claim benefits, how spouses coordinate their benefits, how survivor benefits are protected, and how Social Security interacts with taxes, Medicare, and portfolio withdrawals. Our Social Security Optimization Guide explores these decisions in greater depth and shows why Social Security should be evaluated as part of your broader retirement income strategy.
Inside the guide, you’ll learn about:
Strategic claiming decisions
Spousal and survivor benefits
Coordinating benefits for couples
The tax implications of Social Security
Medicare and IRMAA considerations
Integrating Social Security with your investment portfolio
Advanced Wealth Management integrates Social Security planning with the SWAG™ Retirement Roadmap, helping coordinate claiming decisions with income, taxes, investments, and long-term financial goals.
Your GPS to Holistic Retirement Planning
Understanding Social Security is important. But Social Security alone cannot answer the bigger retirement questions:
Will my income support the lifestyle I want?
How should I coordinate withdrawals from different accounts?
How can I manage taxes throughout retirement?
How do I prepare for healthcare costs and longevity?
How can I make sure my wealth transfers according to my wishes?
That is why I created Your GPS to Holistic Retirement Planning.
Retire once. Stay retired.
Complimentary retirement course + workbook
Let’s build a stronger, smarter plan together.
Schedule your free consultation today.
Important Disclosure: This content is for educational purposes only and should not be considered personalized investment, tax, legal, accounting, insurance, or medical advice. The health-related information is educational and should not be considered medical advice. Always consult your physician or qualified healthcare provider before making changes to your medications, supplements, testing, or health routine. Do not use prescription medications, hormone therapies, growth hormone, DHEA, metformin, or experimental longevity protocols except under the supervision of a qualified medical professional. Trusts, estate planning, asset protection, insurance, and tax strategies should be reviewed with qualified professionals based on your personal situation. Laws vary by state, and no asset protection strategy can guarantee protection from all claims or liabilities. Investing involves risk, including the possible loss of principal. Advisory services are offered through Advanced Wealth Management, LLC, a registered investment adviser in Florida doing business as Boutique Family Office™.